Travellers pick travel protection by weighing their destination, trip cost, planned activities and the medical cover a policy includes. Based on those needs, they can compare policies that cover their trip’s risks without paying for benefits they don’t need.
Yet plenty of people book their flights first and think about insurance last. By then, they’ve already paid for the trip, and any cancellation caused by an earlier event may fall outside their cover.
To avoid similar coverage gaps, this guide explains what travel insurance pays for and which policy terms affect your claims. You’ll also learn how domestic and international cover differ, including why Medicare won’t cover your medical costs overseas.
Let’s jump into it.
What Does Travel Protection Cover When Things Go Wrong?
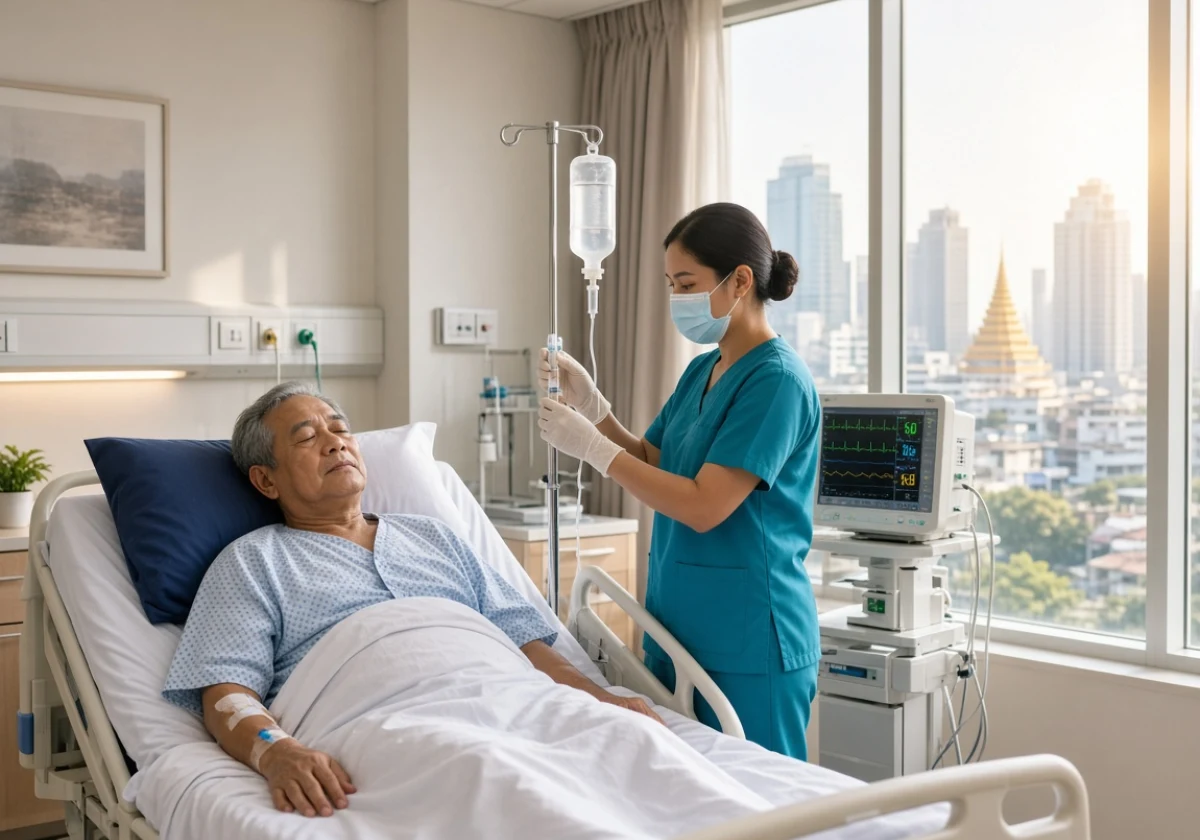
Travel protection covers medical expenses, trip cancellation, lost luggage, and travel delays. However, each benefit has a payout limit and exclusions that determine when the insurer will pay a claim and how much.
Before comparing prices, check how these three coverage areas protect your trip.
Emergency Medical Cover and Evacuation Overseas
Emergency medical bills cost the most, which is why insurers build the plan around them. A few nights in a private hospital in Southeast Asia can easily exceed your entire holiday budget.
Beyond the bill itself, the insurer’s assistance team helps arrange treatment. One call connects you with a team that finds a doctor, checks the hospital and arranges direct payment.
That same team organises evacuation and repatriation when local care can’t manage the injury (the part nobody thinks to budget for beforehand). The same benefit covers your journey home, including medical assistance from a nurse if needed.
Cancellation Cover, Lost Luggage, and Travel Delays
Cancellation cover refunds prepaid costs when illness or a death in the family stops you from travelling. Insurers pay against receipts, so keep every booking confirmation.
Lost luggage works differently, because per-item sub-limits often sit below what a camera or laptop is worth. From what we’ve read across policy booklets, that one line often catches people out, despite the higher headline limit.
Flight delays bring a different set of costs, with travel delay cover paying for meals and accommodation if you’re stranded overnight. However, policies require a minimum delay before cover applies. If the delay extends beyond your scheduled trip dates, contact the insurer’s assistance team.
What About Adventure Sports and Activity Coverage?
Standard policies usually leave them out. Adventure sports sit in optional activity coverage that lifts your premium, and snow trips work the same way.
For these activities, insurers draw the line by named activity. Hiring a moped in Bali requires specific cover and a valid licence, or the insurer could decline your claim (licence rules are easy to overlook).
So read the activity list before you book the lesson or sign the hire form. One missing add-on can leave a broken leg entirely on your card.
Travel Insurance Fine Print: What the Product Disclosure Statement Tells You
A Product Disclosure Statement (PDS) explains what your travel insurance covers, including benefit limits, exclusions and claim conditions. Every insurer publishes one, including nib and Cover-More Travel Insurance. Having read a fair few of them, we can tell you the answers are rarely hidden.
Since policy terms vary between insurers, start by checking these four details.
- Limits and Sub-Limits: Caps sit on every benefit, and smaller sub-limits sit under each item. While medical limits and cancellation caps get the attention, luggage sub-limits often determine how much you’ll receive for individual belongings.
- Target Market Determination: This short document explains who the insurance product suits based on factors like age, destination and trip length. So, check it early to see if the policy suits your travel plans before reading the full PDS.
- Conditions and Exclusions: Check how the policy handles pre-existing medical conditions, alcohol-related incidents and government travel advice. Destination warnings deserve particular attention because some travel alerts may affect your cover. Before you fly, check if any new travel warnings affect your destination.
- Who Carries the Risk: The insurer named in your PDS is responsible for paying eligible claims, even if another company sells the policy. Knowing who the insurer is helps you identify who handles claims and complaints. If the insurer subscribes to Australia’s General Insurance Code of Practice, it must follow the Code’s standards for handling them.
You’ll find a privacy policy and a Financial Services Guide alongside the PDS, though each document serves a different purpose. Comparison sites help you narrow your options, but they don’t always show every policy or exclusion.
Before paying, check the insurer’s full PDS to confirm what your chosen cover includes.
Travel Decisions That Separate Domestic and International Cover
Your destination determines if you need domestic or international travel insurance, so settle that question early. According to the Australian Bureau of Statistics, Indonesia accounted for 18.1% of Australian resident returns during the reporting period.
The table compares domestic and international policy benefits, including single-trip and annual multi-trip cover.
| What changes | Domestic travel | International travel |
|---|---|---|
| Medical bills | Medicare and hospital cover apply | Your policy pays overseas medical costs |
| Cancellation | Covered, on lower trip costs | Covered, with higher limits |
| Emergency help | Local ambulance and hospitals | 24/7 global assistance team |
For domestic trips, focus on cancellation costs, luggage and expenses that Medicare doesn’t cover. International trips need closer attention to overseas medical expenses and emergency evacuation.
Cruises sit between the two, so check how a plan handles onboard medical treatment before you book. Tiers differ as well, since basic policies cap the medical cover low and the dearer ones lift it.
Your Health Insurance Won’t Follow You on Overseas Travel
Australian travellers often assume Medicare or private health insurance follows them overseas. However, Medicare only covers eligible treatment in Australia and doesn’t pay for medical care abroad. Private health insurance generally has similar limits.
Reciprocal health care agreements soften the drop in a handful of countries. Even there, you only get medically necessary public treatment, which leaves private hospitals, repatriation and the flight home on you.
Private health insurance in Australia works the same way. Your fund generally covers treatment within Australia, so don’t assume it’ll pay your overseas medical bills (check with your fund before travelling).
This lack of overseas medical cover is where travel insurance earns its price. An air ambulance off a remote island could cost thousands of dollars. Hospitals overseas also ask for payment before they start treating you.
Before you travel, declare existing medical conditions honestly and save the assistance number in your phone. Otherwise, undeclared conditions could lead to rejected claims, while a saved number gives you quick access to help during an emergency.
Sort Your Travel Protection Before You Pack
Your destination, trip cost and activity list decide which travel insurance fits. The policy wording then decides what you get back, so check the limits and exclusions before you commit to a plan.
As we’ve covered, medical expenses and cancellations have their own policy conditions. Alongside these, mentioned lost luggage and travel delays come with separate limits and exclusions. Domestic and international cover differ too, especially for overseas medical treatment, which Medicare doesn’t cover.
For further guidance, Monkey House Music publishes plain-English guides like this one for travellers who’d rather understand a policy than guess at it. Contact the team to talk through the questions above before you book your next trip.
